RSS


Mortgage Rate Outlook


The growing fears of the potential impact of COVID-19 resulted in a full market meltdown in late February, sending equity markets into free fall and global bond yields plummeting. On top of an already volatile situation, two of the world’s largest oil producers, Saudi Arabi and Russia, have engaged in a price war that sent oil prices to levels not seen since the late 1990s.


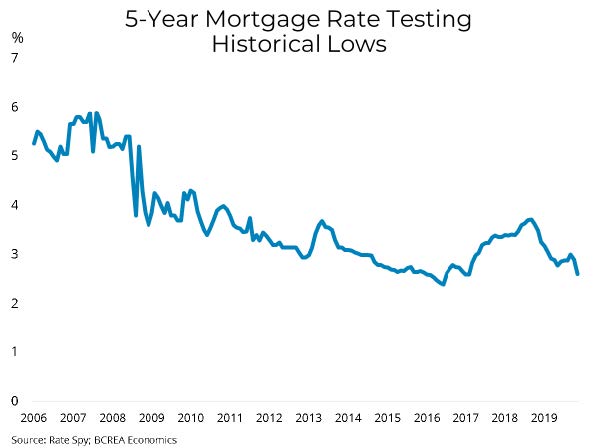
The panic sent Canadian bond yields down sharply and prompted emergency rate cutting by the Bank of Canada. Variable and 5-year fixed qualifying mortgage rates have followed bond yields lower with the 5-year fixed rate reaching 2.59 per cent, its lowest level since 2016 and very near its lowest level on record.


How prolonged and just how serious this outbreak will be is still unknown, which makes forecasting extremely difficult. What we do know is that the economy is in for at least a quarter of significant loss of economic output as measures to stop the spread of COVID-19, such as social distancing, sheltering in place and mandatory business closures, put a halt to economic and social activity.


Though mortgage rates have started rising as risk increases, we anticipate that measures implemented by the government, the Bank of Canada and other global central banks will help to calm fears over financial system liquidity and stem a longer-term spike in bank funding costs. As the economy recovers, mortgage rates will once again decline.


Of note, the Canadian government has postponed changes to the mortgage stress test. The qualifying rate for insured mortgages was set to change from the 5-year posted mortgage rate to the average 5-year fixed rate plus 200 basis points on April 6, with the B-20 stress test for uninsured mortgages to follow suit. By postponing this change, the government has muted the passthrough from monetary policy to the housing market, particularly since the 5-year posted rate has maintained at 5.19 per cent, despite the average 5-year contract rate falling to near historical lows. The impact of dramatically lower rates will still help those renewing or refinancing mortgages at lower rates by freeing up monthly cash flow due to lower mortgage payments.


Click here for more...


Provided by: BCREA


“Copyright British Columbia Real Estate Association. Reprinted with permission.”

Read

Canadian home sales up in February


Statistics released today by the Canadian Real Estate Association (CREA) show national home sales were up between January and February 2020.

Highlights:

  • National home sales climbed 5.9% on a month-over-month (m-o-m) basis in February.
  • Actual (not seasonally adjusted) activity was up 26.9% year-over-year (y-o-y).
  • The number of newly listed properties jumped 7.3% m-o-m.
  • The MLS® Home Price Index (HPI) advanced by 0.7% m-o-m and 5.9% y-o-y.
  • The actual (not seasonally adjusted) national average sale price climbed 15.2% y-o-y.

Home sales recorded over Canadian MLS® Systems rose by 5.9% inFebruary 2020, marking one of the larger m-o-m gains of the past decade.


With transactions up in about 60% of all local markets in February, the big national increase was largely the result of a 15% jump in activity in the Greater Toronto Area (GTA). Many other Central and Southern Ontario markets also posted sizeable sales gains between January and February.


Actual (not seasonally adjusted) sales activity stood 26.9% above February 2019, although sales were quite weak a year ago. February 2019 marked a decade-low for the month, so a good part of the big y-o-y gain reflects low levels of activity recorded at the time. February 2020 also benefited from an additional day due to the leap year.


Transactions surpassed year-ago levels in about 80% of all local markets, including all large urban markets.


“Home prices are accelerating in markets where listings are in increasingly short supply, specifically in Ontario, Quebec and the Maritimes which together account for about two-thirds of national sales activity,” said Jason Stephen, president of CREA. “Meanwhile, ample supply across the Prairies and in Newfoundland and Labrador means increased competition among sellers. Whether you are looking to buy or sell, or both, all real estate is local, and nobody knows that better than a professional REALTOR®, your best source for information and guidance when negotiating the sale or purchase of a home,” said Stephen.


“Following a quieter than normal December/January period, February saw a burst of new listings in some of Canada’s most supply-starved markets, so it was not a surprise that sales were up alongside that increase in new supply,” said Shaun Cathcart, CREA’s Senior Economist. “There is some question about how much pent-up demand remains in parts of the country where listings have been low for some time now. That said, it will take more than one month of increased new listings to even start to turn some of these markets towards some semblance of balance. In the meantime, expect competition among buyers for available listings to continue to drive prices higher.”


The number of newly listed homes jumped 7.3% in February compared to January, more than erasing the declines of late last year. New supply gains were posted in a number of large markets, including the Fraser Valley, Calgary, Edmonton, the GTA, Hamilton-Burlington, Kitchener-Waterloo, Windsor-Essex, Ottawa and Montreal.


With new listings rising by slightly more than sales in February, the national sales-to-new listings ratio fell back to 64% compared to 64.9% posted in January. That said, the bigger picture is that this measure of market balance has been significantly above its long-term average of 53.8% for the last five months. Barring an unforeseen change in these recent trends, home prices appear poised to post further growth in 2020.


Considering the degree and duration to which market balance readings are above or below their long-term averages is the best way of gauging whether local housing market conditions favour buyers or sellers. Market balance measures that are within one standard deviation of their long-term average are generally consistent with balanced market conditions.


Based on a comparison of the sales-to-new listings ratio with the long-term average, about 60% of all local markets were in balanced market territory in February 2020. Apart from a few areas of Alberta and Saskatchewan, the remainder were all favouring sellers.


The number of months of inventory is another important measure of the balance between sales and the supply of listings. It represents how long it would take to liquidate current inventories at the current rate of sales activity.


There were 4.1 months of inventory on a national basis at the end of February 2020 – the lowest level since the summer of 2007. This measure of market balance is now more than a full month below its long-term average of 5.2 months, suggesting sales negotiations are becoming increasingly tilted in favour of sellers.


National measures of market balance continue to mask significant and increasing regional variations. The number of months of inventory has swollen far beyond long-term averages in the Prairie provinces


and Newfoundland & Labrador, giving homebuyers ample choice in these regions. By contrast, the measure is running well below long-term averages in Ontario, Quebec and the Maritime provinces,


resulting in increased competition among buyers for listings and providing fertile ground for price gains. The measure remains in balanced territory in British Columbia.


The Aggregate Composite MLS® Home Price Index (MLS® HPI) rose 0.7% in February 2020 compared to January, marking its ninth consecutive monthly gain.


The MLS® HPI was up in February 2020 compared to the previous month in 15 of the 19 markets tracked by the index. As of this release, Winnipeg is in the MLS® HPI.


Looking at the big Prairie markets, home price trends have ticked downwards in Calgary and Edmonton to start 2020 but have generally been stable since the beginning of last year. Prices in Saskatoon have also been stable over the last year, while those in Regina have continued to trend lower. Prices in Winnipeg have been on a slow upward trend since the beginning of 2019.


Meanwhile, the recovery in home prices remains in full swing in British Columbia and in Ontario’s Greater Golden Horseshoe (GGH) region. Further east, price growth in Ottawa, Montreal and Moncton continues as it has for some time now, with Ottawa and Montreal prices accelerating to start 2020.


Comparing home prices to year-ago levels yields considerable variations across the country, although for the most part trends are still regionally split along east/west lines, with rising gains from Ontario east, and a mixed bag of smaller gains and declines in B.C. and the Prairies.


The actual (not seasonally adjusted) Aggregate Composite MLS® HPI rose 5.9% y-o-y, the biggest year-over-year gain since February 2018.


Prices are now back in positive y-o-y territory in both Greater Vancouver (+0.3%) and the Fraser Valley (+1.4%). Elsewhere in British Columbia, home prices logged y-o-y increases in the Okanagan Valley (+3.9%), Victoria (+4.3%) and elsewhere on Vancouver Island (+3.2%).


Calgary and Edmonton continued to post small y-o-y price declines, while the y-o-y gap was -5.4% in Regina. Prices in Saskatoon (+1.1%) and Winnipeg (+1.6%) both posted a small y-o-y increases in February.


In Ontario, home price growth has re-accelerated across the GGH, with a number of markets posting double-digit growth as of February. Meanwhile, price gains in recent years have continued uninterrupted in Ottawa (+14.7%), Montreal (+10.4%) and Moncton (+7.5%).


All benchmark home categories tracked by the index accelerated further into positive territory on a y-o-y basis, with similar sized gains among the different property types.


Two-storey single family homes posted the biggest y-o-y increase (+6.2%) followed closely by prices for apartment units (+6%), one-storey single-family homes (+5.4%) and townhouse/row units (+5.1%).


The MLS® HPI provides the best way to gauge price trends because averages are strongly distorted by changes in the mix of sales activity from one month to the next.


The actual (not seasonally adjusted) national average price for homes sold in February 2020 was around $540,000, up 15.2% from the same month the previous year.


The national average price is heavily influenced by sales in the GVA and GTA, two of Canada’s most active and expensive housing markets. Excluding these two markets from calculations cuts close to $130,000 from the national average price, trimming it to around $410,000.


Provided by: CREA

Read

BC Home Sales Trend Higher in February

The British Columbia Real Estate Association (BCREA) reports that a total of 5,741 residential unit sales were recorded by the Multiple Listing Service® (MLS® ) in February 2020, an increase of 26.3 per cent from February 2019. The average MLS® residential price in BC was $758,863, a 12 per cent increase from $677,681 recorded the previous year. Total sales dollar volume in February was $4.4 billion, a 41.4 per cent increase over 2019.


“Housing markets in BC continued to trend near long-term average levels in February,” said BCREA Chief Economist Brendon Ogmundson. “Recent declines in mortgage rates and favourable changes to mortgage qualifying rules may provide a boost to home sales heading into the spring, although there is significant economic uncertainty lingering over the outlook.”


Total MLS® residential active listings fell 8.4 per cent to 28,303 units compared to the same month last year. The ratio of sales to active residential listings increased 20.3 per cent from 14.7 per cent last February.


Year-to-date, BC residential sales dollar volume was up 38.4 per cent to $7.6 billion, compared with the same period in 2019. Residential unit sales increased 24.8 per cent to 10,135 units, while the average MLS® residential price was up 10.9 per cent to $745,501.


Click here for more...


Provied by: BCREA

Read

Just Listed: C322 20211 66th Ave, Langley, Willoughby Heights

Excellent Central Location

Rental and Pet Friendly

Price at $474,800

Open: Sat Mar 14 from 1 to 3


Click here for more details


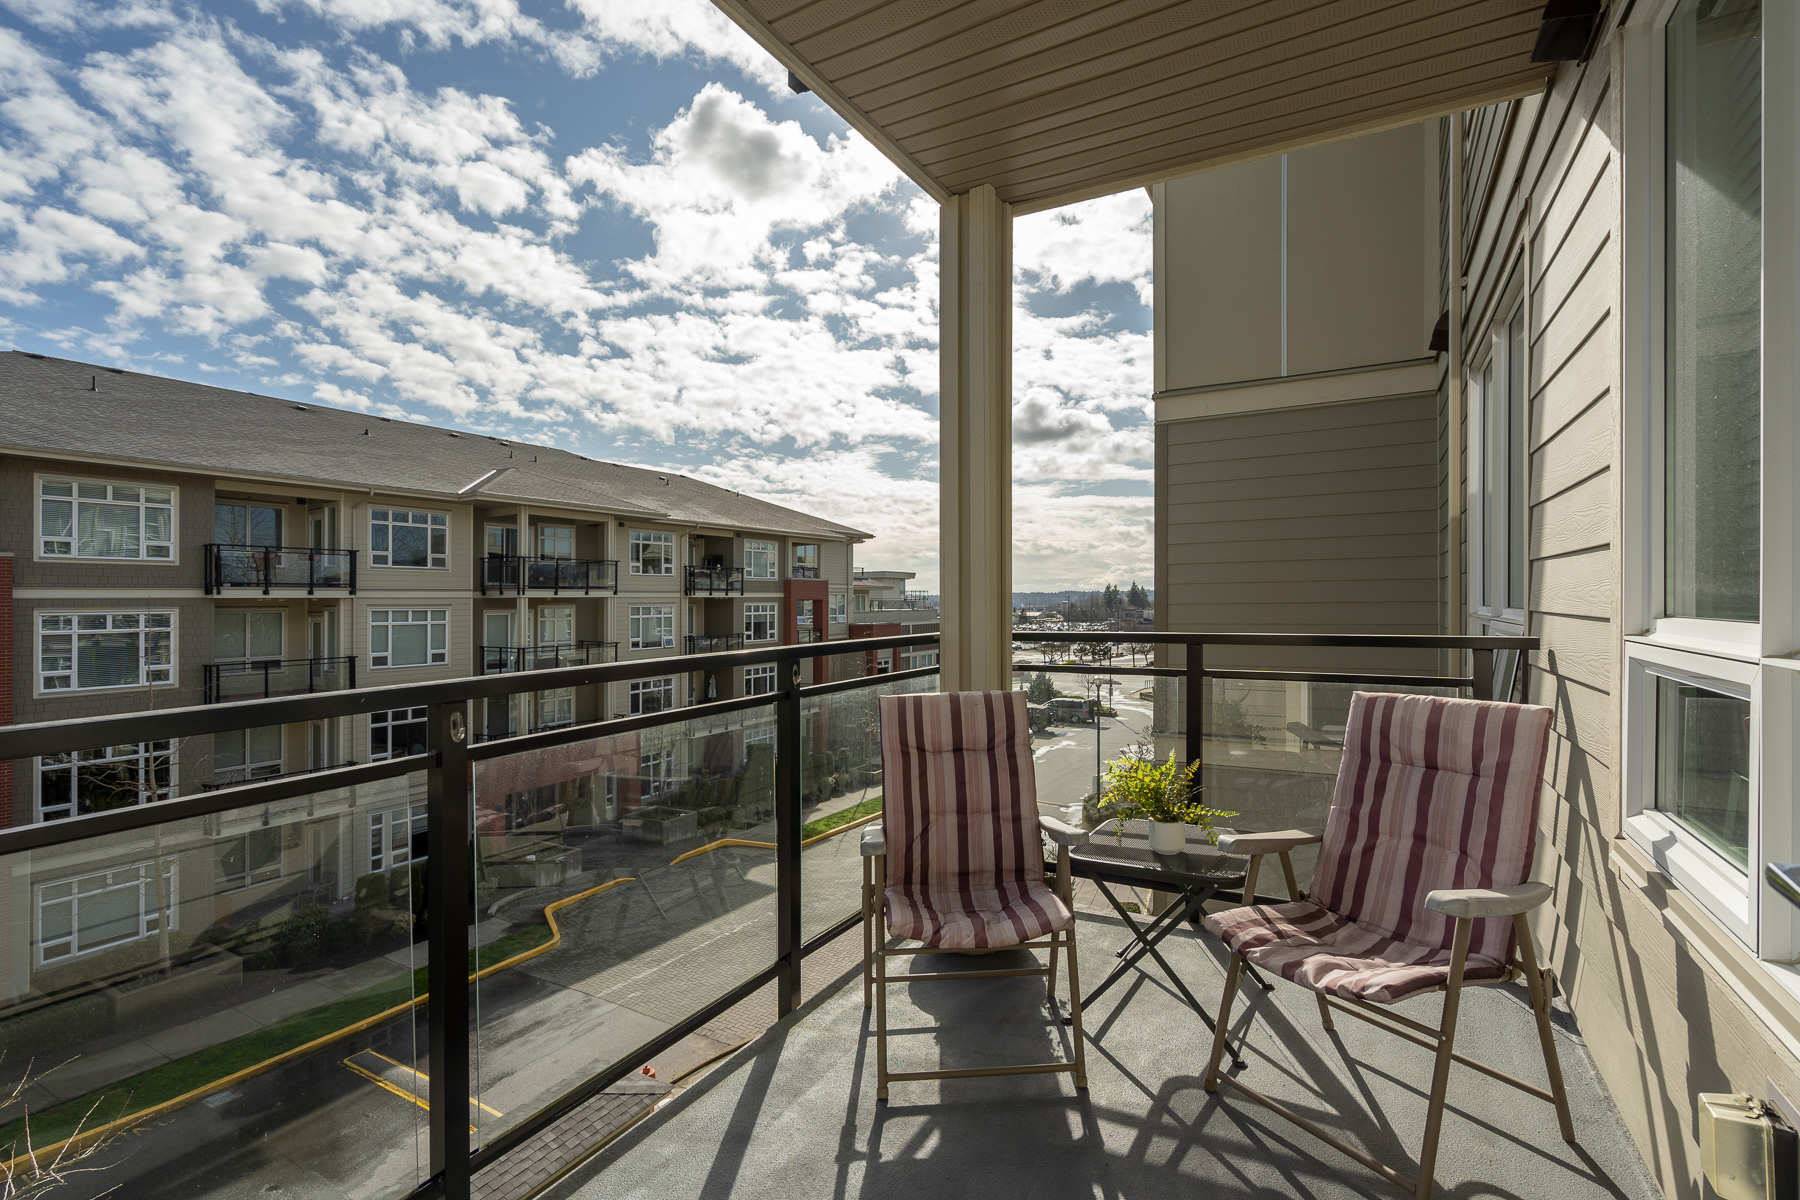
Bright, open and functional are just a few ways to describe this fantastic unit. Located in the popular Elements building in the desirable Willoughby Heights neighborhood of Langley, with a location that can't be beat. Welcome home! Features: modern finishing, over height ceilings, spacious layout, laminate floors through & newer carpets in the bedrooms, a spacious kitchen w/plenty cupboard & granite counters space & SS apps, laundry closet w/extra storage & an excellent sized balcony perfect for BBQs. The large master has passthrough closets & 3 pc spa inspired ensuite while the 2nd bed is well sized. Bonus: 1 parking, locker on your floor & rental & pet friendly. Located close to shopping, recreation, transit, schools, parks and more. Act Now! Open Sat Mar 14 from 1 to 3.

Read

Just Listed: 411 Mundy Rd., Coquitlam, BC

Central Coquitlam

4 Bedrooms on Top Floor

Price at $1,424,800

Open Houses

Saturday March 7th from 2 to 4

Sunday March 8th from 2 to 4o


Click here from more details


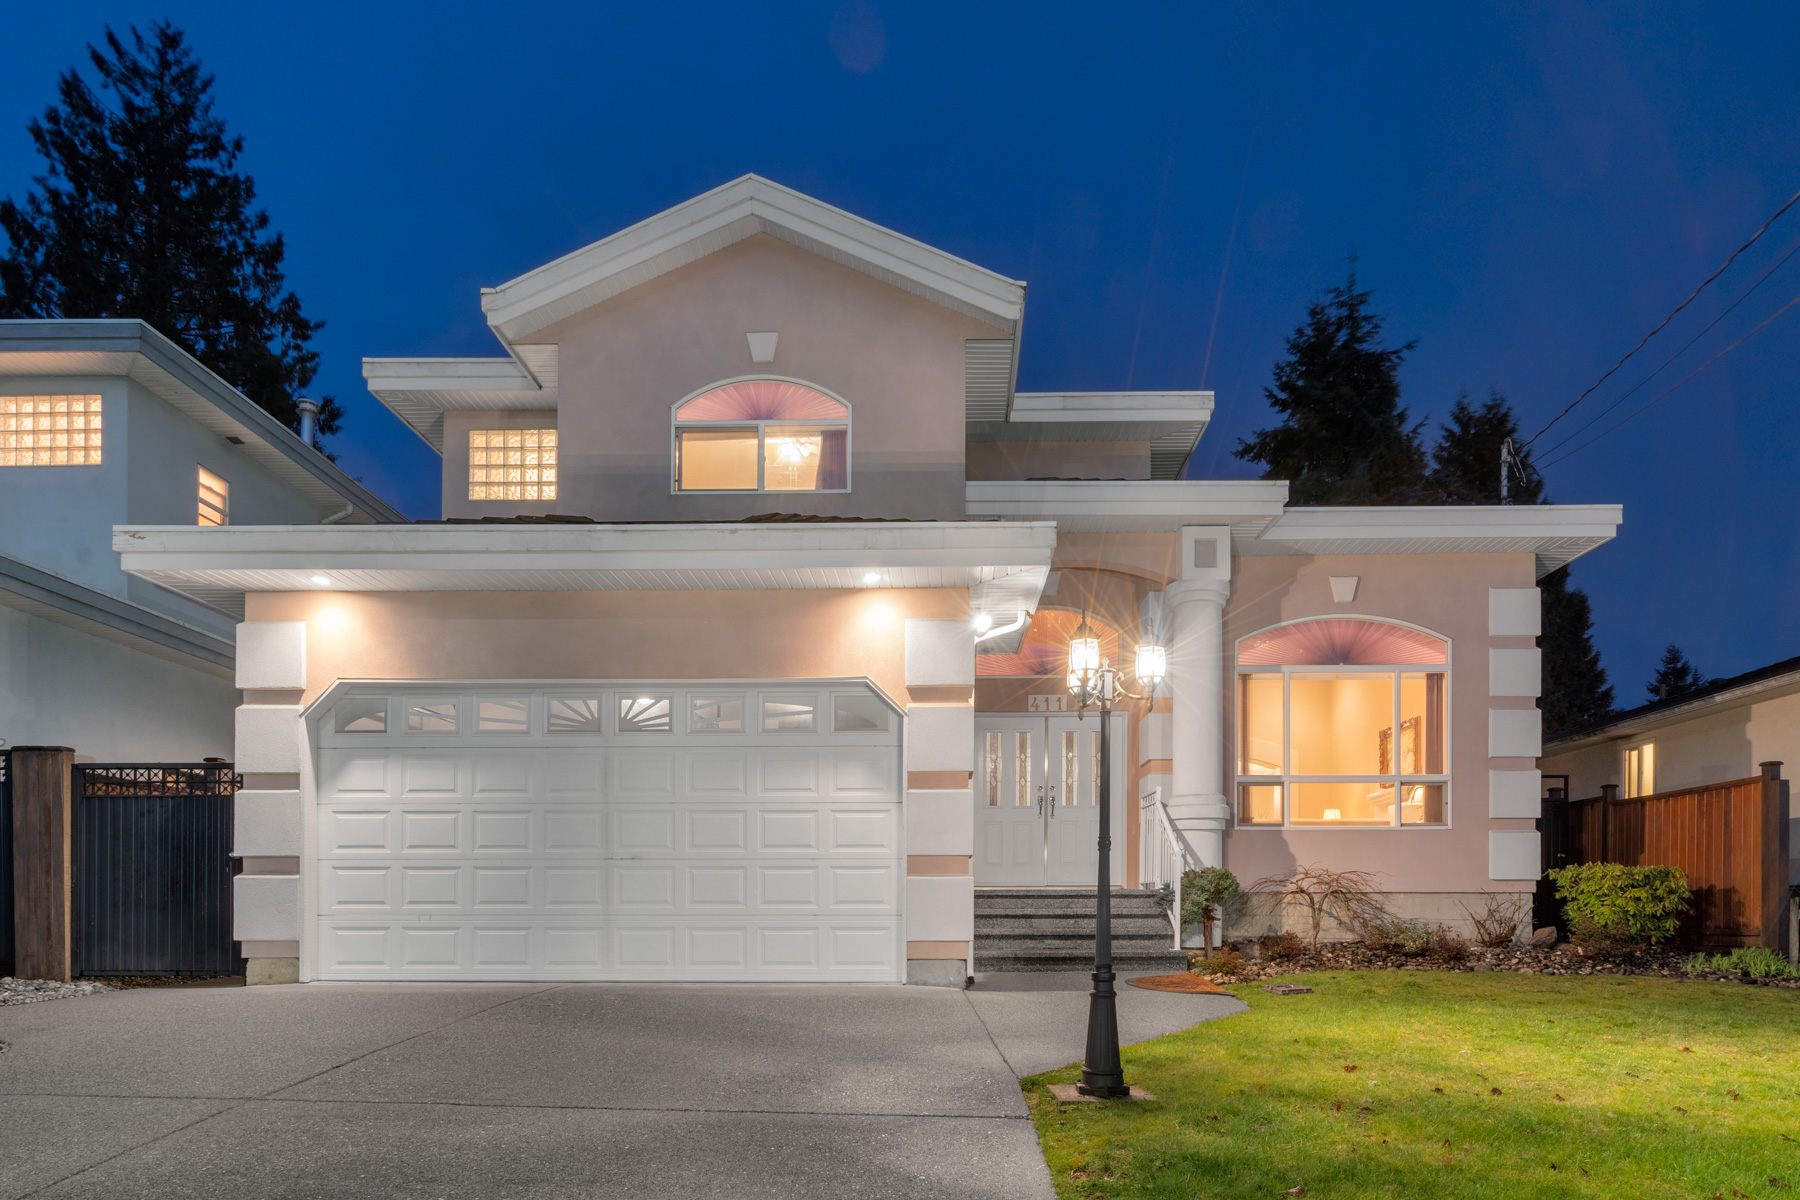
Immaculate custom-built home on level lot with private yard, located in desirable Central Coquitlam with highly sought 4 bed on top floor layout. Welcome home! This 7bed/4bath/3489sqft/2lvl/22year young home features: grand entrance w/semi-spiral staircase, formal living & dining rooms, large kitchen w/plenty of cupboard & counter space, island, eating area, new SS apps & direct patio/yard access; perfect for entertaining. Family room w/cozy gas F/P, bedroom, 2pc powder, laundry & access to oversized dble car garage complete the main level. Up offers huge master w/5pc ensuite, walk-in closet & den & 3 excellent sized rooms & main bath. Bonus: bright, above ground 2bed in-law suite. Close to: transit, schools, shopping, rec. Mundy Park & more. Act Now! Open

Read

Steady demand and low supply benefits home sellers

VANCOUVER, BC – March 3, 2020 – February saw steady home buyer demand and reduced home seller supply across Metro Vancouver*.


The Real Estate Board of Greater Vancouver (REBGV) reports that residential home sales in the region totalled 2,150 in February 2020, a 44.9 per cent increase from the 1,484 sales recorded in February 2019, and a 36.9 per cent increase from the 1,571 homes sold in January 2020.


Last month’s sales were 15.6 per cent below the 10-year February sales average.

“Home buyer demand again saw strong year-over-year increases in February while the total inventory of homes for sale struggled to keep pace,” Ashley Smith, REBGV president said. “This was most pronounced in the condominium market.”


There were 4,002 detached, attached and apartment homes newly listed for sale on the Multiple Listing Service® (MLS®) in Metro Vancouver in February 2020. This represents a 2.8 per cent increase compared to the 3,892 homes listed in February 2019 and a 3.4 per cent increase compared to January 2020 when 3,872 homes were listed.


The total number of homes currently listed for sale on the MLS® system in Metro Vancouver is 9,195, a 20.7 per cent decrease compared to February 2019 (11,590) and a 6.7 per cent increase compared to January 2020 (8,617).


"Our Realtors are reporting increased traffic at open houses and multiple offer scenarios in certain pockets of the market. If you’re considering listing your home for sale, now is a good time to act with increased demand, reduced competition from other sellers, and some upward pressure on prices," says Smith.


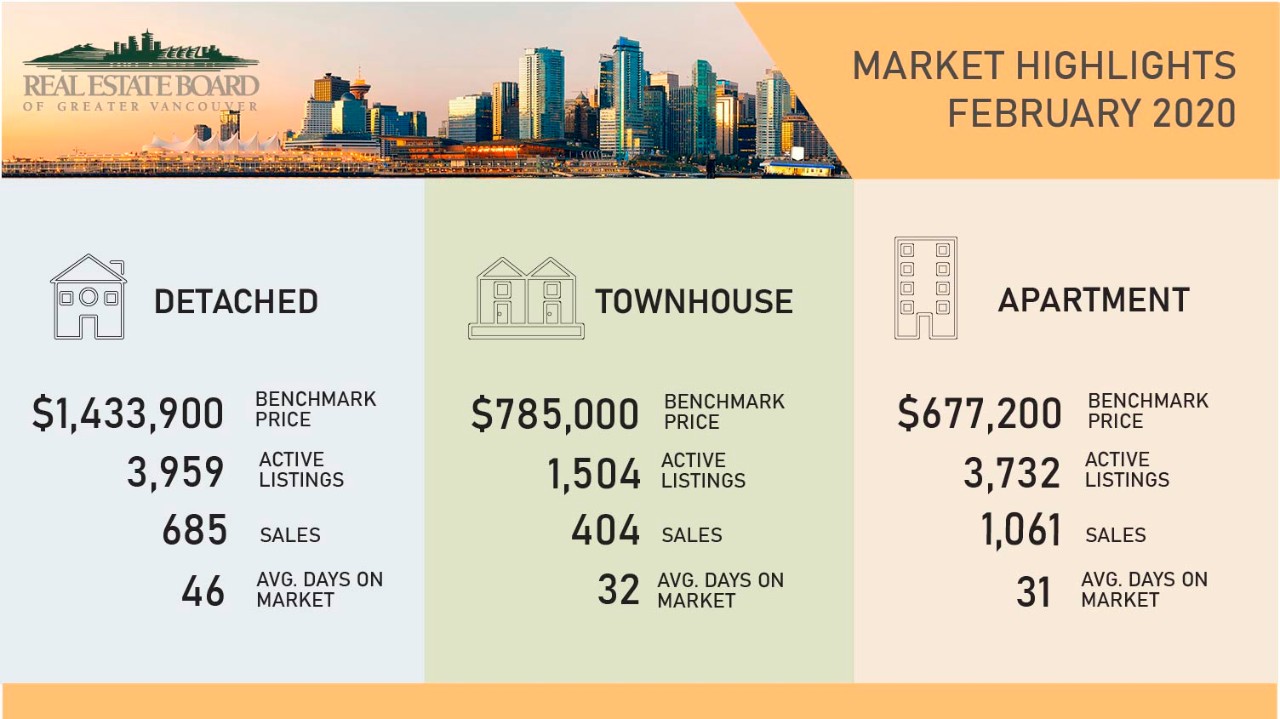
For all property types, the sales-to-active listings ratio for February 2020 is 23.4 per cent. By property type, the ratio is 17.3 per cent for detached homes, 26.9 per cent for townhomes, and 28.4 per cent for apartments.


Generally, analysts say downward pressure on home prices occurs when the ratio dips below 12 per cent for a sustained period, while home prices often experience upward pressure when it surpasses 20 per cent over several months.


The MLS® Home Price Index composite benchmark price for all residential properties in Metro Vancouver is currently $1,020,600. This represents a 0.3 per cent increase over February 2019 and a 2.7 per cent increase over the past six months.


Sales of detached homes in February 2020 reached 685, a 52.9 per cent increase from the 448 detached sales recorded in February 2019. The benchmark price for a detached home is $1,433,900. This represents a 0.7 per cent decrease from February 2019 and a 1.9 per cent increase over the past six months.


Sales of apartment homes reached 1,061 in February 2020, a 39.8 per cent increase compared to the 759 sales in February 2019. The benchmark price of an apartment property is $677,200. This represents a 0.9 per cent increase from February 2019 and a 3.6 per cent increase over the past six months.


Attached home sales in February 2020 totalled 404, a 45.8 per cent increase compared to the 277 sales in February 2019. The benchmark price of an attached home is $785,000. This represents a 0.6 per cent increase from February 2019 and a 1.7 per cent increase over the past six months.


*Editor’s Note: Areas covered by the Real Estate Board of Greater Vancouver include: Burnaby, Coquitlam, Maple Ridge, New Westminster, North Vancouver, Pitt Meadows, Port Coquitlam, Port Moody, Richmond, South Delta, Squamish, Sunshine Coast, Vancouver, West Vancouver, and Whistler. The real estate industry is a key economic driver in British Columbia. In 2019, 25,351 homes changed ownership in the Board’s area, generating $1.8 billion in economic spin-off activity and an estimated 12,910 jobs. The total dollar value of residential sales transacted through the MLS® system in Greater Vancouver totalled $25.3 billion in 2019. The Real Estate Board of Greater Vancouver is an association representing approximately 14,000 REALTORS® and their companies. The Board provides a variety of member services, including the Multiple Listing Service®. For more information on real estate, statistics, and buying or selling a home, contact a local REALTOR® or visit www.rebgv.org

Read

Just Sold: 402 22722 Lougheed Hwy., Maple Ridge, East Central

Fully Renovated

Top Floor

Price at $298,800


Click here for more...


Top floor, extensively renovated, green space facing, centrally located; your search ends here. This massive 1bed/1bath/851sqft West facing home, located in Mark's Place of East Central Maple Ridge, will not disappoint! Upgrades: fresh paint, brand new carpet & vinyl floors, LED light fixtures, new faucets, new closet doors & brushed nickel hardware, upgraded bathroom w/vanity, lighting & mirror, new fireplace surround; nothing to do but move right in. Features: large living & dining areas, spacious kitchen w/plenty of cupboard & counter space & eating area, covered balcony, functional laundry rm & plenty of storage space. Enjoy the huge master w/lots of closet space & access to balcony. Close to: shopping, recreation, transit, parks & schools. Act Now! 

Read

Many strata owners are facing significant increases in insurance premiums and deductibles. While the word "crisis" is used often in media articles, BCREA believes long-term government policy changes should be made very carefully and with as much information as possible.


There are about 30,000 strata corporations in BC and at least one-quarter of the population lives in strata units. Higher insurance costs for strata corporations get passed down to owners in the form of increased strata fees. If the increases are significant, then there's a negative impact on housing affordability.


The current situation developed over several years. Commonly cited causes for the rising cost of strata insurance include the size and location of the buildings, materials used, claims history, the high value of real estate and high costs of repairs.


BCREA was pleased to see the Insurance Bureau of Canada form its Commercial Task Force, and we welcome the opportunity to discuss this issue with a wide variety of stakeholders in March. In the meantime, we're examining potential big picture government policy changes and looking at other jurisdictions so we can be part of the solution.

In the short term, though, there are two pressing concerns:

  1. Some strata corporations are struggling to get and renew insurance. We encourage strata corporations with this problem to contact the Insurance Bureau of Canada (1.844.227.5422). Doing so could help you find insurance and will also help us all understand the scope of this problem. 
  2. Potential buyers of individual units need to know how to navigate the uncertainty. REALTORS® working with these potential buyers have clauses they can put into Contracts of Purchase and Sale to get insurance information. To make sure all buyers are informed, BCREA has recommended that Minister of Municipal Affairs and Housing Selina Robinson amend the Form B Information Certificate to require proof of insurance. This form has to be completed when strata properties change hands.
Provided by: Norma Miller for BCREA
Read

Earlier today, Minister of Finance Bill Morneau announced changes to the mortgage stress test.


The new benchmark rate used to determine the minimum qualifying rate for insured mortgages, coming into effect on April 6, 2020, will be the weekly median 5-year fixed insured mortgage rate from mortgage insurance applications, plus 2 per cent.


Recently, the gap between the Bank of Canada’s five-year benchmark rate and borrowers’ actual contract rates has been widening, suggesting the benchmark rate has become less responsive to changes in the market.


In October 2016, Finance Canada introduced a stress test for insured mortgages. In 2017, the Office of the Superintendent of Financial Institutions (OSFI) issued an update to Guideline B-20, requiring uninsured mortgages to be stress-tested as of January 2018. CREA data indicates that per capita sales activity for residential units in 2018 reached its lowest point since 2001, with 2019’s final sales total tied for second-worst.


“REALTORS® have advocated for changes to the stress test on behalf of potential homeowners who have been sidelined, borrowers who have moved away from the regulated market to less-regulated options, and real estate markets across the country in need of relief,” said Jason Stephen, President of The Canadian Real Estate Association.


“We are pleased the government has taken steps to address some of these issues in Canadian housing markets.”


In response to the impacts of the stress test, CREA has recommended:

  • reviewing the mortgage stress test to ensure the realities of local real estate markets are taken into consideration; and
  • allowing existing mortgage holders to be exempted from the stress test at the time of renewal.

CREA welcomes today’s announcement and acknowledges government’s efforts to help Canadians achieve their housing needs through policy reflective of market conditions.


CREA CEO Michael Bourque said “Today’s announcement introduces a more dynamic measure to act as a minimum qualifying rate. The Bank of Canada’s weekly median 5-year fixed insured mortgage rate plus 200 basis points will be more responsive.”


CREA will be providing input as OSFI considers the same benchmark rate for uninsured mortgages and will continue advocating for policy solutions that make it easier for Canadians to find a home that is right for them.


Provided by: CREA

Read

Just Sold: 407 Draycott St., Coquitlam, Central Coquitlam

Prime, level lot in Central Coquitlam

Price at $1,100,000


Click here for more...


Located in a quiet family friendly neighborhood with no through traffic. This 7840sqft corner lot measuring approximately 80' X 98' offers lane access and City views. Potentially a livable home with renovations. Massive detached workshop for all your toys, tools and storage needs. Ideally suited for a developer or someone looking to build their dream home.  Drive by anytime. Call now for more details.

Read

For many Canadians, their home is the most important investment they will make in their lifetime. That is why the Government of Canada has introduced measures to help more Canadians achieve their housing needs while also taking measured actions to contain risks in the housing market. A stable and healthy housing market is part of a strong economy, which is vital to building and supporting a strong middle class.


Today, Minister of Finance, Bill Morneau, announced changes to the benchmark rate used to determine the minimum qualifying rate for insured mortgages, also known as the “stress test.” These changes will come into effect on April 6, 2020. The new benchmark rate will be the weekly median 5-year fixed insured mortgage rate from mortgage insurance applications, plus 2%.


This follows a recent review by federal financial agencies which concluded that the minimum qualifying rate should be more dynamic to better reflect the evolution of market conditions. Overall, the review concluded that mortgage standards are working to ensure that home buyers are able to afford their homes even if interest rates rise, incomes change, or families are faced with unforeseen expenses. This adjustment to the stress test will allow it to be more representative of the mortgage rates offered by lenders and more responsive to market conditions.


The Office of the Superintendent of Financial Institutions (OSFI) also announced today that it is considering the same new benchmark rate to determine the minimum qualifying rate for uninsured mortgages. OSFI is seeking input from interested stakeholders on this proposal before March 17, 2020.

Quotes

“For many middle class Canadians, their home is the most important investment they will make in their lifetime. Our government has a responsibility to ensure that investment is protected and to support a stable housing market. The government will continue to monitor the housing market and make changes as appropriate. Reviewing the stress test ensures it is responsive to market conditions.”

Bill Morneau, Minister of Finance

Quick facts

  • When a borrower has less than a 20% down payment, lenders are required to obtain government-backed mortgage insurance. The mortgages must comply with the insured mortgage rules set by the Minister of Finance, including the insured minimum qualifying rate.

  • When the borrower has a down payment of 20%, or more, of the sale price, insurance is not required. The minimum qualifying rate for uninsured mortgages is set by OSFI, the independent banking regulator.

  • To help more Canadians access affordable housing that meets their needs, the Government of Canada launched the National Housing Strategy—a 10-year, $55+ billion plan that will build 125,000 new affordable housing units, repair 300,000 others, and reduce chronic homelessness by 50%.

  • In Budget 2019, the federal government took concrete steps to make homeownership more affordable for first-time buyers by implementing a First-Time Home Buyer Incentive and increasing the Registered Retirement Savings Plan withdrawal limit to $35,000 to buy a home. 

Provided by: Government of Canada

Read

Canadian home sales down in January

Statistics released today by the Canadian Real Estate Association (CREA) show national home sales declined between December 2019 and January 2020.


Highlights:

  • National home sales fell by 2.9% on a month-over-month (m-o-m) basis in January.
  • Actual (not seasonally adjusted) activity was up 11.5% year-over-year (y-o-y).
  • The number of newly listed properties was little changed (+0.2%) m-o-m.
  • The MLS® Home Price Index (HPI) advanced by 0.8% m-o-m and 4.7% y-o-y.
  • The actual (not seasonally adjusted) national average sale price climbed 11.2% y-o-y.

Home sales recorded over Canadian MLS® Systems declined by 2.9% in January 2020, although they remain among the stronger monthly readings of the last few years. (Chart A)


Transactions were down in a little over half of all local markets in January, with the national result most impacted by a slowdown of more than 18% in the Lower Mainland of British Columbia. While there were few notable gains in January, it should be noted that many of the weaker results have come alongside a shortage of new supply in markets where inventories are already very tight.


Actual (not seasonally adjusted) sales activity was still up 11.5% compared to January 2019, marking the best sales figures for the month in 12 years. Transactions surpassed year-ago levels in about two-thirds of all local markets, including most of the largest urban markets. As mentioned, some of the larger markets where sales were down, such as Ottawa and Windsor-Essex, are currently among some of the tightest supplied markets in Canada.


“Home price growth continues to pick up in housing markets where listings are in short supply, particularly in Southern, Central and Eastern Ontario,” said Jason Stephen, president of CREA. “Meanwhile, ample supply across the Prairies and in Newfoundland and Labrador is resulting in ongoing competition among sellers. All real estate is local, and nobody knows that better than a professional REALTOR®, your best source for information and guidance when negotiating the sale or purchase of a home,” said Stephen.


“Looking at local market trends across the country, one thing that stands out in markets with historically tight supply is a larger than normal drop in new listings at this time of the year,” said Shaun Cathcart, CREA’s Senior Economist. “The logic being that if you are a seller, you’re not just choosing when to list but effectively when to sell, so why not hold off until the spring when the weather is better, and more buyers are looking? Deferred listings mean deferred sales, which could explain some of January’s decline in activity. The question going forward is how many sellers are out there waiting to list their property, how much demand will respond, and how that will impact prices later this year.”


The number of newly listed homes was little changed in January, edging up a slight 0.2% on the heels of a series of declines which have left new listings at a near decade low. January’s small m-o-m change came as the result of declines in a number of larger markets, including Calgary, Edmonton and Montreal, which were offset by gains in the York and Durham Regions of the Greater Toronto Area (GTA) where new supply bounced back at the start of 2020 following a sharp slowdown towards the end of last year.


With sales down and new listings up slightly in January, the national sales-to-new listings ratio fell back to 65.1% compared to 67.2% posted in December 2019. Even so, the long-term average for this measure of housing market balance is 53.8%. It has been significantly above that long-term average for the last four months. Barring an unforeseen change in recent trends between the balance of supply and demand for homes, price gains appear poised to accelerate in 2020.


Considering the degree and duration to which market balance readings are above or below their long-term averages is the best way of gauging whether local housing market conditions favour buyers or sellers. Market balance measures that are within one standard deviation of their long-term average are generally consistent with balanced market conditions.


Based on a comparison of the sales-to-new listings ratio with the long-term average, close to two-thirds of all local markets were in balanced market territory in January 2020. Apart from a few areas of Alberta and Saskatchewan, the remainder were all favouring sellers.


The number of months of inventory is another important measure of the balance between sales and the supply of listings. It represents how long it would take to liquidate current inventories at the current rate of sales activity.


There were 4.2 months of inventory on a national basis at the end of January 2020 – the same as in November and December and the lowest level since the summer of 2007. This measure of market balance is now a full month below its long-term average of 5.2 months. While still just within balanced market territory, its current reading suggests that sales negotiations are becoming increasingly tilted in favour of sellers.


National measures of market balance continue to mask significant and increasing regional variations. The number of months of inventory has swollen far beyond long-term averages in the Prairie provinces and Newfoundland & Labrador, giving homebuyers ample choice in these regions. By contrast, the measure is running well below long-term averages in Ontario, Quebec and the Maritime provinces, resulting in increased competition among buyers for listings and providing fertile ground for price gains. The measure is still in balanced market territory in British Columbia.


The Aggregate Composite MLS® Home Price Index (MLS® HPI) rose 0.8% in January 2020 compared to December, marking its eighth consecutive monthly gain. It is now up 5.5% from last year’s lowest point in May and has set new records in each of the past six months. (Chart B)


The MLS® HPI in January was up from the previous month in 14 of the 18 markets tracked by the index. (Table 1)


Home price trends have generally been stabilizing in most Prairie markets in recent months following lengthy declines. Meanwhile, prices are clearly on the rise again in British Columbia and in Ontario’s Greater Golden Horseshoe (GGH). Further east, price growth in Ottawa, Montreal and Moncton continues as it has for some time now, with Montreal and particularly Ottawa having strengthened noticeably in recent months.


Comparing home prices to year-ago levels yields considerable variations across the country, although for the most part trends are still regionally split along east/west lines, with rising gains from Ontario east, and a mixed bag of smaller gains and declines in B.C. and the Prairies.


The actual (not seasonally adjusted) Aggregate Composite MLS® (HPI) rose 4.7% y-o-y in January, the biggest year-over-year gain since February 2018.


Home prices in Greater Vancouver (-1.2%) remain slightly below year-ago levels, but declines are still shrinking. Meanwhile, January saw prices back in positive y-o-y territory in the Fraser Valley (+0.3%). Elsewhere in British Columbia, home prices logged y-o-y increases in the Okanagan Valley (+3.5%), Victoria (+3.4%) and elsewhere on Vancouver Island (+4%).


Calgary, Edmonton and Saskatoon continued to post small y-o-y price declines, while the y-o-y gap has now widened to -6.9% in Regina.


In Ontario, home price growth has re-accelerated across most of the GGH, with a number of markets getting close to double digits. Meanwhile, price gains in recent years have continued uninterrupted in Ottawa (+13.7%), Montreal (+9.8%) and Moncton (+6.4%).


All benchmark home categories tracked by the index accelerated further into positive territory on a y-o-y basis, with similar sized gains among the different property types.


Apartment unit prices posted the biggest y-o-y increase (+5%) followed closely by two-storey single family homes (+4.8%), one-storey single-family homes (+4.4%) and townhouse/row units (+4.2%).


The MLS® HPI provides the best way to gauge price trends, because averages are strongly distorted by changes in the mix of sales activity from one month to the next.


The actual (not seasonally adjusted) national average price for homes sold in January 2020 was around $504,350, up 11.2% from the same month the previous year. This was the largest increase since mid-2016.


The national average price is heavily influenced by sales in the GVA and GTA, two of Canada’s most active and expensive housing markets. Excluding these two markets from calculations cuts close to $110,000 from the national average price, trimming it to around $395,000.


Provided by: CREA

Read
Reciprocity Logo The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.